
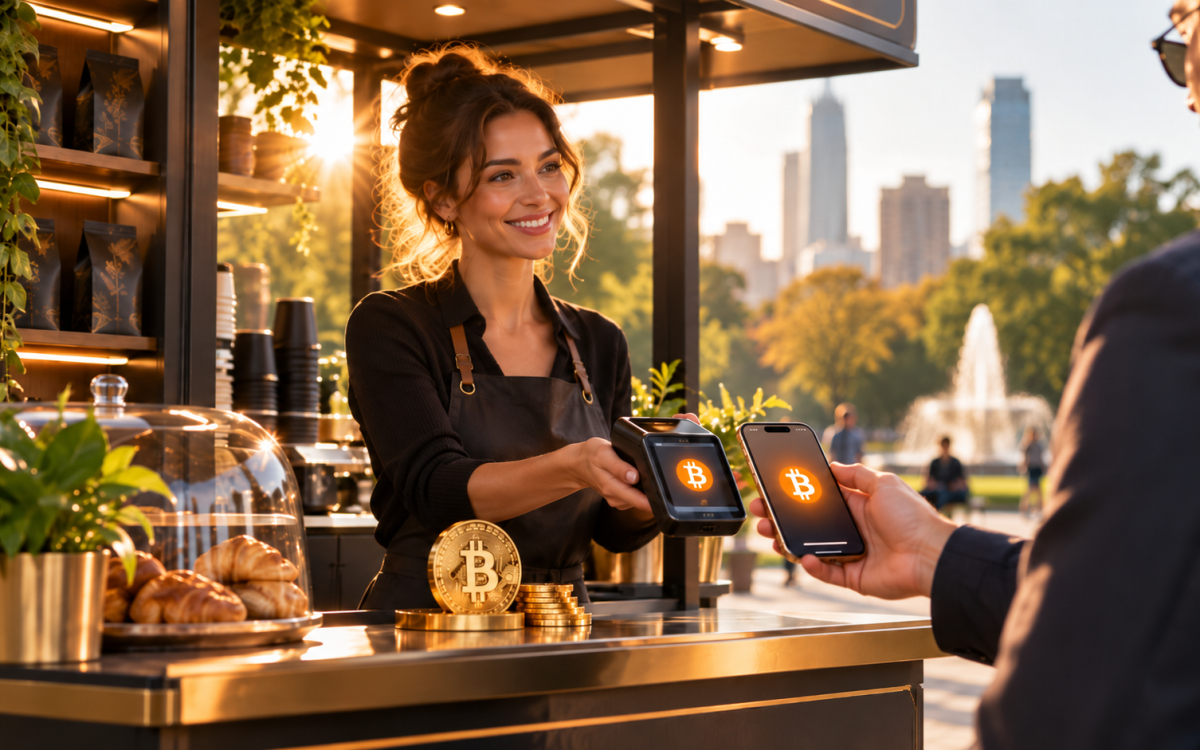
Crypto is becoming easier for small businesses to use without building a complicated wallet or payment system from scratch.
In 2026, merchants can accept Bitcoin or stablecoins through familiar payment platforms, sometimes with automatic conversion into dollars or another local currency.
For example, Shopify now supports USD Coin (USDC) payments through Shopify Payments in eligible regions, Square supports Bitcoin payments for eligible US sellers, and PayPal lets approved US merchants accept payments from buyers using a wide range of cryptocurrencies.
That does not mean every small business needs crypto. The practical question is whether it solves a real problem, such as expensive international payments, customer demand for crypto checkout, slow settlement, or limited access to traditional payment rails.
For businesses with those problems, crypto has become much easier to test in 2026.
Crypto Payments Are Easier to Add Than Before
One of the biggest changes since the earlier version of this article is that crypto payments no longer always require a separate crypto-native checkout system.
Shopify Payments lets eligible merchants offer USDC at checkout. Customers can pay from supported crypto wallets, while merchants can choose how they receive proceeds. Shopify launched the feature with Coinbase and Stripe, initially using the Base network.
Square has also expanded Bitcoin payments. Eligible US sellers can accept Bitcoin through the Lightning Network and choose settlement in either Bitcoin or US dollars, with payments settling in seconds and funds appearing in the seller’s dashboard shortly afterward.
PayPal‘s Pay with Crypto product takes a different approach. Eligible US merchants can accept payments funded with supported cryptocurrencies while PayPal automatically converts the transaction and settles the merchant in local currency. The service currently supports around 100 cryptocurrencies and payments from both exchange accounts and self-custody wallets.
For a small business, this removes one of the biggest barriers to crypto adoption: the merchant doesn’t necessarily need to hold cryptocurrency at all.
Crypto Can Reduce Payment Costs, but Not Always
The old claim that crypto payments are always significantly cheaper than credit cards is too broad.
Costs depend on the payment provider, blockchain, settlement method, and transaction type.
For example, PayPal’s current US Pay with Crypto merchant rate is 1.50% as of August 1, 2026. Its standard domestic credit and debit card rate is 2.99% plus a fixed fee, while PayPal Checkout is generally 3.49% plus a fixed fee
Square currently charges eligible sellers 0% for Bitcoin payments through the end of 2026; the processing fee moves to 1% after December 31, 2026. By comparison, its standard Free-plan rate is 2.6% plus $0.15 for many in-person card transactions and 3.3% plus $0.30 for online payments.
That could make crypto cheaper in some setups, especially for certain cross-border or Bitcoin Lightning transactions.
But merchants should compare the full cost rather than assuming blockchain payments are automatically cheaper. Network fees, payment processor charges, conversion spreads, withdrawal costs, and accounting expenses can change the final result.
| Payment Method | Example 2026 Cost | Main Consideration |
| PayPal Pay with Crypto | 1.5% | Merchant receives local currency |
| PayPal standard cards | 2.99% + fixed fee | Familiar card checkout |
| Square Bitcoin | 0% through Dec. 31, 2026 | Eligible sellers and locations only |
| Square in-person card | From 2.6% + $0.15 | Depends on Square plan |
| Square online payment | From 3.3% + $0.30 | Depends on Square plan |
Table 1. Examples of Crypto and Card Processing Costs in 2026
These are platform examples rather than universal industry rates. Businesses should check their own processor, region, and account pricing before comparing costs.
Stablecoins Are Becoming More Useful for Business Payments
Bitcoin and Ethereum are still widely recognized crypto assets, but stablecoins can make more sense for businesses that do not want large price swings.
A stablecoin is a cryptocurrency designed to track another asset, usually a fiat currency such as the US dollar. USDC and USDT, for example, are designed to maintain a value close to $1.
They can be especially useful for international business because they can move across blockchain networks without requiring traditional correspondent banking for every transfer.
For example, a US business paying an overseas contractor may be able to use a dollar-denominated stablecoin instead of sending an international wire. The recipient still needs a suitable wallet and a legal way to convert or use the stablecoin in their country.
Stablecoins also carry risks. Their value depends on the issuer, reserves, redemption arrangements, and network being used. “Stable” does not mean risk-free.
Faster Settlement Can Help Cash Flow
Traditional card payments may appear instantly at checkout while actual merchant settlement can take longer. Crypto settlement can sometimes happen much faster.
Square’s Bitcoin payments use the Lightning Network and can settle in seconds. PayPal also says its crypto conversion happens near instantly, although the merchant’s payout then follows PayPal’s normal funding schedule.
Blockchain settlement may be fast, but when funds reach a bank account still depends on the service used.
Businesses that receive crypto directly into their own wallets can avoid some of those banking delays, but they then take on custody, conversion, and accounting responsibilities themselves.
Cross-Border Businesses Have More to Gain
Crypto can be most useful when a business regularly sells to customers or pays suppliers across borders.
For context, traditional international payments can involve foreign exchange fees, correspondent banks, card surcharges, and delays between financial institutions.
That said, crypto can remove some of those steps.
Shopify’s stablecoin checkout lets eligible merchants receive payments from customers using supported wallets, while PayPal’s crypto product lets US merchants accept crypto-funded purchases from global buyers.
This does not make crypto universally cheaper or faster than every bank transfer. Domestic real-time payment systems and services such as Automated Clearing House (ACH) transfers can already be inexpensive.
The advantage becomes more noticeable when the alternative is a costly international card payment or wire transfer.
Businesses Do Not Have to Hold Volatile Crypto
One common misconception is that accepting crypto means a business has to keep Bitcoin or Ethereum on its balance sheet. Many payment providers make that unnecessary.
Square lets sellers choose whether Bitcoin payments settle in Bitcoin or dollars. PayPal converts accepted crypto into the merchant’s settlement currency, while Shopify merchants can choose between eligible payout options depending on their setup.
Automatic conversion can help a bakery, retailer, or freelance business offer crypto checkout without speculating on the asset’s price.
Holding the crypto instead creates a separate financial decision. If a merchant receives $1,000 worth of Bitcoin and keeps it, the value may rise or fall significantly after the sale. That market exposure should be treated separately from whether crypto is useful as a payment method.
Crypto Does Not Automatically Mean More Privacy
Public blockchains keep transaction histories on a public ledger. Wallet addresses are pseudonymous, but transactions can often be traced and analyzed.
Businesses using payment processors may also need to complete identity, business, and compliance checks.
PayPal, for example, requires eligible merchants to complete its onboarding and compliance process before activating crypto payments. Shopify can also request additional business information before approving a merchant for USDC payments.
Crypto therefore changes how payment data moves, but it should not be assumed to be anonymous by default.
Chargebacks Work Differently With Crypto
Traditional card payments allow customers to dispute transactions through their bank or card issuer.
Native blockchain transactions generally do not have the same chargeback mechanism.
PayPal states that payments through its Pay with Crypto service are irrevocable and are not subject to traditional disputes or chargebacks.
For merchants, this can reduce exposure to certain types of chargeback fraud.
It also moves more responsibility to the business.
If a customer sends crypto to the wrong address or a merchant mistakenly refunds the wrong wallet, the blockchain transaction itself may not be reversible.
Businesses still need clear refund procedures, customer support, and fraud controls even when the underlying payment cannot be reversed.
Wallet Access Can Help Businesses Outside Traditional Banking
A crypto wallet can generally be created without applying for a bank account or undergoing a credit check, giving entrepreneurs another way to receive or store digital assets, particularly in regions where access to traditional financial services is limited.
However, having a wallet does not remove every financial barrier. A business may still need identity verification to use a regulated exchange, convert crypto into local currency, or connect to a commercial payment processor. Local laws can also restrict which crypto services are available.
Crypto can expand payment access, but it should not be presented as a complete replacement for banking in every market.
Security Comes With Different Responsibilities
Blockchain records are difficult to alter once transactions are confirmed, but that does not automatically make a crypto business setup safer than traditional payments.
Therefore, the risks are different. Businesses holding their own crypto need to protect wallet credentials and private keys. Losing access to a self-custody wallet can mean losing access to the funds permanently.
Phishing, fake wallet software, compromised devices, and incorrect wallet addresses are also practical risks.
Businesses that do not want to manage those risks themselves can use a payment provider that automatically converts incoming crypto into fiat currency.
However, the trade-off is that the merchant then depends on the provider’s security, availability, account rules, and compliance requirements.
Crypto Payments Create Tax and Accounting Work
Small business owners also need to consider recordkeeping before adding crypto checkout.
In the United States, the Internal Revenue Service (IRS) treats digital assets as property, not currency, for federal tax purposes. Digital assets received as payment for goods or services must generally be valued in US dollars and reported as business income.
If the business keeps the crypto and later sells or exchanges it, that later transaction may create a separate gain or loss.
The IRS says taxpayers should maintain records showing the type of digital asset, transaction date, amount, fair market value, and basis where applicable.
Reporting infrastructure is also changing. Certain digital asset brokers began reporting gross proceeds for transactions from January 1, 2025, and basis reporting applies to certain covered digital assets for transactions beginning in 2026.
Meanwhile, businesses outside the US must follow their local tax and accounting rules.
Crypto Is Most Useful When It Solves a Specific Business Problem
Adding crypto because it is fashionable is not a strong business case. A better approach is to identify where the existing payment system causes friction.
Crypto may be useful when:
- Customers are already asking to pay with Bitcoin or stablecoins.
- A business has substantial international sales.
- Cross-border payment fees are high.
- Contractors or suppliers prefer digital assets.
- Settlement speed is important.
- The merchant wants an additional payment option without holding crypto itself.
It may offer much less benefit when almost every customer pays locally by card, cash, or inexpensive bank transfer.
A business should also consider refund handling, accounting workload, customer support, volatility and local regulation before switching on crypto payments.
Should Your Small Business Accept Crypto in 2026?
Crypto payments have become more practical for ordinary businesses, but the strongest reason to use them is utility, not hype.
In some cases, processing costs can also be lower than card payments, while blockchain networks can make cross-border settlement faster.
Those benefits come with additional responsibilities. Businesses still need to understand taxes, refunds, custody, security, and the rules that apply in their country.
For many small businesses, the sensible first step is not replacing cards or bank transfers. It is offering crypto as one additional payment option, measuring whether customers actually use it, and comparing the real cost against existing payment methods.
Frequently Asked Questions
Need a refresher? Here are some common questions small business owners have about using crypto in 2026.
Can a Small Business Accept Bitcoin?
Yes. Businesses can accept Bitcoin directly to a wallet or through a payment processor. Square, for example, allows eligible US sellers to accept Bitcoin over the Lightning Network and settle the payment in either Bitcoin or US dollars.
Do I Need a Crypto Wallet to Accept Crypto Payments?
Not always. Services such as PayPal can accept a customer’s crypto payment and automatically settle the merchant in traditional currency. Businesses that choose to receive crypto directly will generally need a suitable wallet.
Are Crypto Payments Cheaper Than Credit Cards?
Sometimes, but not universally. PayPal’s Pay with Crypto rate is currently 1.5%, compared with higher rates for several of its card products, while Square is charging eligible sellers 0% for Bitcoin payments through the end of 2026. Other providers and networks may have different fees.
Is It Better for a Business to Accept Bitcoin or Stablecoins?
That depends on the business. Bitcoin may appeal to customers who already hold BTC, while dollar-linked stablecoins can reduce short-term price volatility for merchants. Businesses can also use processors that immediately convert either asset type into fiat currency.
Do Businesses Pay Tax on Crypto Payments?
In the US, digital assets received for goods or services are generally taxable business income based on their fair market value when received. If the business keeps the crypto and later disposes of it, that can create an additional taxable gain or loss. Other countries have their own rules.